Jessica Hassan
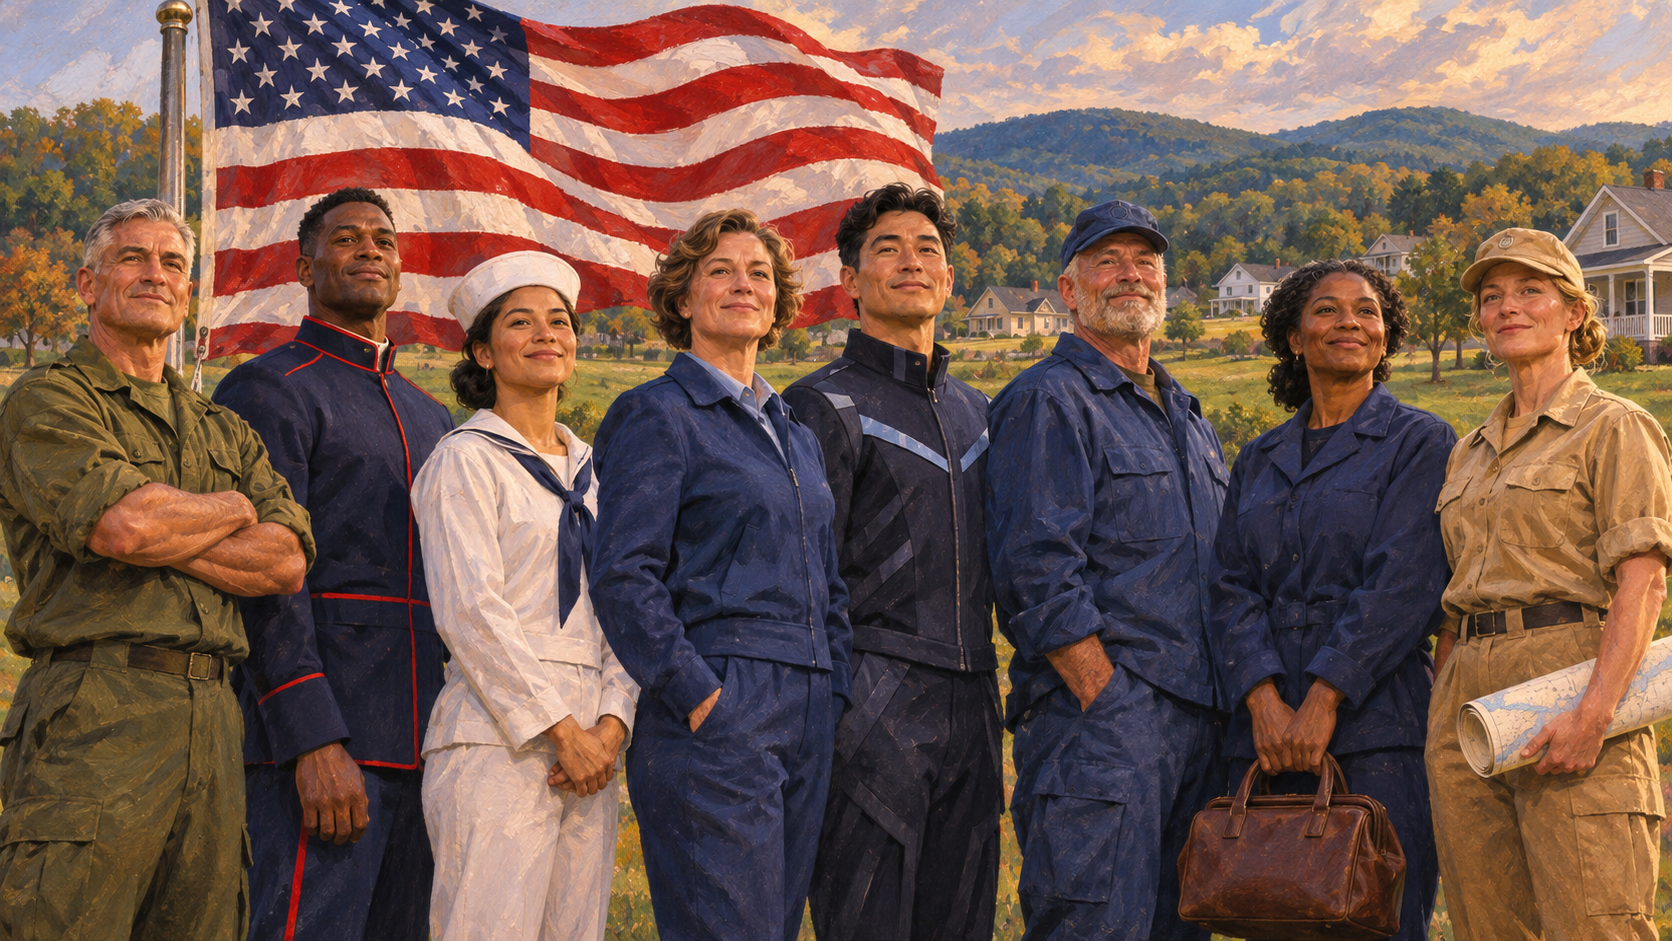
This Veterans Day, thank you to the veterans who have served our country and to the families who have supported them. Your service, time away from home and commitment to others deserve recognition on November 11 and throughout the year.
We honor veterans of the Army, Marine Corps, Navy, Air Force, Space Force and Coast Guard, including those who served in the National Guard and Reserve. We also recognize the service of the U.S. Public Health Service Commissioned Corps and NOAA Commissioned Officer Corps, the other two U.S. uniformed services, and thank those serving today.
For a veteran planning a home purchase, sale or move, a useful thank-you includes clear information. This guide explains where to start with VA financing, what to protect when selling a home with a VA loan, and which official resources can help you settle into Northern Alabama. Benefits depend on your service history and individual circumstances; recognition of service is not a determination of eligibility.
Choose the resource that matches your next step
| Your next step | Start here | What this helps you establish |
|---|---|---|
| Buy a primary home | VA eligibility and Certificate of Eligibility | Whether your service qualifies for the loan benefit; a lender separately evaluates financing. |
| Sell a home with a VA loan | Your current loan servicer and VA home loan support | Payoff, assumption requirements and the effect on your remaining entitlement. |
| Make a military move | Plan My Move | A customizable moving checklist organized around your circumstances. |
| Adapt a home for a disability | VA disability housing grants | Whether SAH, SHA or temporary-residence assistance may fit your situation. |
| Get help with mortgage payments | Your servicer and VA foreclosure-avoidance assistance | Available help before missed payments become a larger problem. |
Buying: establish eligibility, then compare the full cost
A Certificate of Eligibility, often called a COE, tells a lender that you meet the VA program’s service requirements. You can request it through VA or ask a lender to help. Veterans, active-duty service members, qualifying Guard and Reserve members, and certain surviving spouses may qualify through different eligibility paths. A COE does not replace the lender’s review of credit, income and other requirements. A VA-backed purchase loan is for a home you intend to occupy, not a general investment-property loan. VA’s eligibility guidance explains the service categories and exceptions.
VA-backed purchase loans can offer no down payment and no monthly mortgage insurance. That does not mean every purchase needs no cash. An appraisal gap, insufficient remaining entitlement, closing costs or a lender’s requirements can affect what you need to bring. With full entitlement, VA does not impose a county loan limit, but lender approval and the property’s value still matter. If you have used the benefit before, have the lender review the entitlement on your current COE rather than assuming it has reset. See VA purchase-loan benefits and entitlement and loan limits.
Compare more than the advertised rate. Ask competing lenders for estimates using the same purchase price, down payment, loan type and rate-lock assumptions. Compare monthly principal and interest, property taxes, homeowners insurance, any HOA charges, lender fees, discount points and cash needed at closing. Keep a separate reserve for moving and repairs. VA’s home-buying process explains why shopping lenders and reviewing the closing paperwork matter.
A funding-fee example, not a loan quote
Under VA’s published purchase-loan schedule, a nonexempt first-time user putting less than 5% down has a 2.15% funding fee. On a hypothetical $300,000 base loan, that is $6,450. Financing that fee would make the balance $306,450 before interest; it does not eliminate other closing costs. Subsequent use and larger down payments can change the fee. Some borrowers, including qualifying recipients of service-connected disability compensation, are exempt. Have the lender verify your status using VA’s current fee and exemption guidance.
That same VA guidance distinguishes ordinary closing-cost credits from seller concessions. The cap is 4% of the home’s VA reasonable value and applies to the defined concessions, not to every seller-paid closing cost. Have your lender classify the proposed credit before negotiating the contract.
Keep the inspection and appraisal separate
A VA appraisal addresses value and program property requirements. It is not a home inspection or a guarantee that the house has no defects. VA recommends a separate inspection. Discuss inspection timing, repair negotiations and the required VA escape clause with your agent and lender before signing. These are separate protections, and the contract’s actual terms matter. VA explains the buying steps and appraisal distinction.
Selling: protect your next use of the VA benefit
If you have a VA loan, request a current payoff and discuss how the sale will affect your entitlement before planning your next purchase. Selling the property and paying the loan in full can support restoration of entitlement, but obtain the updated determination rather than budgeting around an assumption. VA explains restoration and reuse.
A buyer may be interested in assuming your existing VA loan. An assumption is not simply handing over the mortgage payment. The servicer must process the transaction and evaluate the buyer under the applicable rules. Two questions deserve separate written answers:
- Will you be released from liability? This concerns your responsibility for the existing debt.
- Will your entitlement be restored? A release of liability alone does not restore it. An eligible veteran buyer with sufficient entitlement may substitute their entitlement through the approved process; without substitution, the seller’s entitlement can remain tied to the loan.
VA’s assumption guidance explains that distinction. Get the servicer’s requirements and proposed timing before agreeing to a closing date.
The buyer also needs a plan for the difference between the price and assumed balance. In a hypothetical $350,000 sale with a $250,000 remaining loan, the $100,000 difference does not disappear because the loan is assumable. This arithmetic excludes fees and closing adjustments. Any additional financing needs its own approval. Compare the complete proposed transaction, including your next-home plans, rather than only the existing interest rate.
Relocating: connect the moving plan to the housing decision
For a permanent change of station, Military OneSource’s Plan My Move lets you build a personalized checklist. Pair it with the transportation office’s instructions for your orders. A checklist does not establish reimbursement eligibility or authorize an expense.
Before committing to a North Alabama home, put four dates side by side: your reporting date, the earliest realistic possession date, your household-goods delivery window and the end of your current housing commitment. A short gap may call for temporary lodging or storage. A longer overlap belongs in the budget before you make an offer. Retirement, separation, a civilian job move and military orders can have different moving benefits, so use the guidance for your own status.
If your move is connected to Redstone Arsenal, the official Relocation Readiness program offers newcomer support and connections for housing, schools and household needs. Its page identifies service members, family members and eligible civilian employees among the audiences it serves. Confirm the specific service and installation-entry arrangements for your circumstances before traveling there; veteran status alone is not an all-access pass.
For the housing search itself, use my Redstone worksite-first home-search guide to compare actual reporting locations and daily routines. A listing’s distance from the Arsenal boundary is not the full commute. If recreation access matters to your choice, the separate household recreation-access guide explains why each person’s eligibility matters.
Keep official documents with the lender, VA or appropriate benefits office through their secure channels. Your real-estate planning conversation can focus on budget, timing, location and property needs without circulating discharge paperwork, disability records or financial account details.
Local benefits help and Alabama property-tax questions
The Alabama Department of Veterans Affairs maintains an official county service-office directory. Its accredited service officers help veterans, dependents and survivors navigate benefits and claims. These are useful starting points in Northern Alabama:
| Area | Office listed by ADVA | Telephone |
|---|---|---|
| Limestone County | Athens, 1109 West Market Street, Suite B | 256-233-6459 |
| Madison County | Huntsville, 819 Cook Avenue NW, Suite 137 | 256-532-1662 |
| Morgan County | Decatur, 302 Lee Street NE, first floor | 256-351-4635 |
| Colbert and Lauderdale counties | Florence, 312 South Court Street | 256-760-5845 |
| Marshall County | Guntersville, 424 Blount Avenue, Suite 34 | 256-571-7761 |
Use the directory for other counties and current arrangements. Call ahead about appointments, documents and holiday closures, especially around Veterans Day.
For property taxes, start with the Alabama Department of Revenue’s homestead-exemption guidance and the assessing official in the county where the home is located. Potential exemptions have different requirements, including disability-related provisions. Do not assume veteran status automatically makes a property tax-free or subtract an unapproved exemption from your monthly budget. Ask the county which application and supporting documents apply, and when an approved exemption would take effect.
Help adapting a home or keeping the one you have
VA’s Specially Adapted Housing and Special Home Adaptation grants serve veterans and service members with qualifying service-connected disabilities. A Temporary Residence Adaptation grant may apply to an eligible person living temporarily in a family member’s home. These are distinct programs with specific disability and ownership requirements. Start the grant conversation before treating a renovation allowance as money available for a purchase. Grant maximums change by fiscal year, so use VA’s current determination rather than an older dollar figure in a search result.
If mortgage payments are becoming difficult, contact your servicer promptly. You can also call VA home loan support at 877-827-3702. VA offers foreclosure-avoidance counseling to veterans and surviving spouses even when the mortgage is not VA-guaranteed. VA’s assistance page describes available paths, and its contact page lists loan support. Help does not require waiting until a home is listed for sale, and no third party should promise a guaranteed outcome.
A thank-you that continues beyond Veterans Day
Whether you are buying your first home, selling before another move, adapting a home or staying in a community you love, you deserve clear answers and a plan that respects your circumstances. Start with the resource for the decision in front of you, then bring the financing, housing and moving pieces together.
To our veterans and to everyone who has supported them: thank you. We are grateful for your service and for the many ways you continue to contribute to our communities.
Want Personalized Real Estate Help?
If you are buying, selling or relocating in Northern Alabama, contact me to talk through your timing, home priorities and next step. I can help with the real-estate plan while your lender, VA and benefits professionals handle their respective eligibility and financial decisions.
For a move connected to the Arsenal, you can also browse homes in the broader Redstone area. This is a geographic starting point, not a list of VA-approved homes or a guarantee of commute time.
Sharing is Caring:
Author
Sources and review notes
Official resources reviewed November 10, 2026. This article provides general information, not individual lending, legal, tax or benefits advice. Featured image: original AI-generated symbolic tribute to all eight U.S. uniformed services, not a photograph of actual people, an official uniform guide or an endorsement by any service.